
Green Hydrogen Market Trends, Leading Companies, Company Revenue / Sales Performance, Installed Capacity, Production Output, Grid Expansion, Market Share, Technology Adoption, and Industry Outlook
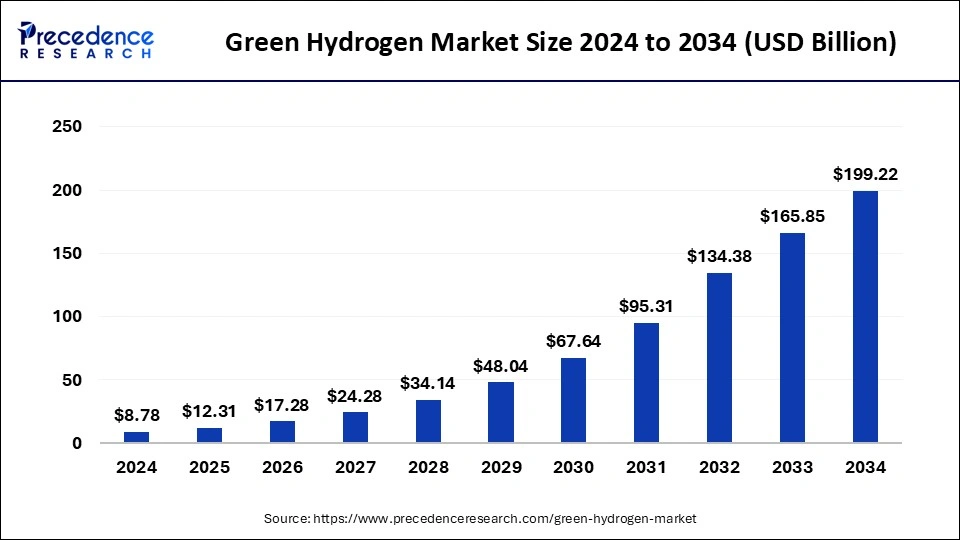
According to energy and power expert Laxmi Narayan, the green hydrogen market has reached USD 17.28 billion in 2026 and is expected to grow to USD 231.32 billion by 2035, registering a CAGR of 34.09%. The green hydrogen market companies such as NEL ASA, ENGIE, Siemens Energy, are playing a key role in market expansion, with major opportunities emerging across by source, by electrolyzer, by end use and region.
Source: https://www.precedenceresearch.com/green-hydrogen-market
 Get a Sample
 Table Of Content


What is the Green Hydrogen Market Size?
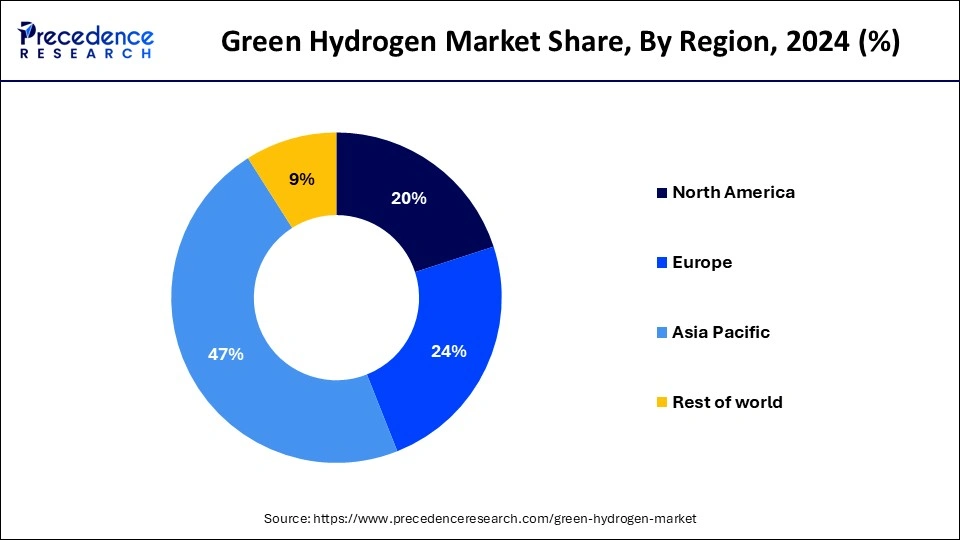
The green hydrogen market size was valued at USD 17.28 billion in 2026 and is projected to reach approximately USD 231.32 billion by 2035, growing at a CAGR of 34.09% from 2026 to 2035, reflecting a fast-expanding green hydrogen market share picture globally. This growth is being driven by government decarbonization initiatives, falling renewable energy costs, ongoing technological advancements, and rising investment in green hydrogen production infrastructure. Asia Pacific led the market with a 47.40% share in 2025. By source, wind energy dominated with a 47.75% share, while PEM electrolyzers accounted for 26.43% of the electrolyzer segment, and refining represented 41.90% of end-use demand.
Market Highlights
- Asia Pacific region has contributed the highest revenue share of over 47.40% in 2025.
- By source, the wind segment has captured a revenue share of over 47.75% in 2025.
- By electrolyzer, the PEM electrolyzer segment has generated a revenue share of over 26.43% in 2025.
- By End User, the refining segment has generated revenue 41.90% in 2025.
What is the Green Hydrogen Market?
At its core, green hydrogen production concentrates on producing hydrogen fuel with zero emissions, achieved by splitting water through electrolysis hydrogen technology powered entirely by renewable sources such as solar and wind. Unlike hydrogen derived from coal or oil, green hydrogen releases only water vapor, leaving no harmful residue behind.
Hydrogen already plays a role in the energy mix of countries such as the United States, Russia, China, France, and Germany, while nations like Japan are working toward becoming full hydrogen economies. Demand continues to build, largely due to green hydrogen's ability to cut carbon emissions across a wide range of industries. Over the next five to ten years, the transportation sector, particularly heavy-duty vehicles, is expected to be one of the strongest drivers of demand.
How has AI benefited the green hydrogen market?
AI in green hydrogen market applications has become a useful tool across the value chain, helping companies make smarter decisions, cut waste, and improve energy efficiency. This shift toward AI hydrogen production optimization allows AI to track hydrogen production in real time, particularly during electrolysis, and when paired with smart sensors, it allows operators to catch problems early before they escalate. It can also forecast energy demand and help determine the optimal time to produce hydrogen based on electricity pricing and available renewable capacity. In Germany and Japan, several companies are already using AI to run large hydrogen plants more efficiently than before. AI is also being applied to hydrogen transport and storage, helping evaluate routes based on cost and safety before shipments even begin. Taken together, AI is helping make the green hydrogen production process faster, cheaper, and cleaner.
Siemens Energy offers a good example of this in practice, having used AI to manage hydrogen production more effectively, resulting in improved energy efficiency and lower operating costs.
Green Hydrogen Market Growth Factors
- One of the biggest factors behind green hydrogen cost reduction is the falling cost of production. As renewable energy becomes more affordable, the cost of producing green hydrogen through electrolysis continues to decline as well.
- Growing economies of scale are also helping bring costs down further, making green hydrogen increasingly competitive with traditional fossil fuels.
- At the same time, expanding government initiatives and subsidies aimed at achieving net-zero emissions, combined with rising investment in renewable hydrogen infrastructure, continue to reinforce the broader green hydrogen market drivers propelling growth.
- Active research and development, paired with ongoing technological progress, is helping drive more efficient and innovative solutions in green hydrogen production, shaping broader industry trends.
Green Hydrogen Market Outlook
- Industry Growth Overview: This green hydrogen industry outlook points to exponential growth between 2025 and 2034, driven by global decarbonization efforts, falling renewable energy costs, and advances in electrolysis technology. High-growth sectors within the broader decarbonization technology market include hard-to-decarbonized industries such as steel, chemical production (particularly ammonia and methanol), and heavy-duty transportation, including trucks, ships, and aviation.
- Sustainability Trends: Sustainability remains the core driver of this market, with the primary focus on producing hydrogen through zero-emission methods using solar, wind, and hydro power to displace fossil fuels in industrial and energy applications. Key trends include the growth of the solid oxide electrolysis market, using processes such as Solid Oxide Electrolysis Cells that make use of waste heat, along with the establishment of stronger green hydrogen certification standards and data privacy measures.
- Global Expansion: The market holds significant potential for green hydrogen market expansion, with major investments and projects underway across Europe, Asia-Pacific, North America, the Middle East, Africa, and Latin America. Asia-Pacific, led by China and India, remains at the forefront of production capacity and continues to see rapidly growing demand. Europe, particularly Germany, France, and the UK, leads in policy support and infrastructure development, while countries such as Chile and Saudi Arabia are leveraging their abundant solar and wind resources to position themselves as major green hydrogen export hubs.
- Major Investors: Green hydrogen investment continues to flow in from a diverse mix of industrial giants, energy multinationals, and venture capital firms, drawn by strong government incentives such as the U.S. Inflation Reduction Act tax credits and India's National Green Hydrogen Mission funding. Leading corporate investors driving the hydrogen electrolyzer market include Air Liquide, Linde plc, Siemens Energy, Plug Power, Cummins Inc., Adani Group, and BP.
- Startup Ecosystem: The ecosystem of green hydrogen startups continues to mature, with growing focus on cost-effective, scalable technologies, particularly in advanced PEM electrolyzer technology design across PEM, SOEC, and AEM types, integration with renewable energy sources, and the development of Robotics-as-a-Service (RaaS) models for infrastructure management. Emerging companies are attracting significant venture capital funding by offering solutions for the efficient production, storage, and transportation of green hydrogen.
Market Scope
| Report Coverage | Details |
| Market Size by 2035 | USD 231.32 Billion |
| Market Size in 2025 | USD 12.31 Billion |
| Market Size in 2026 | USD 17.28 Billion |
| Growth Rate From 2026 to 2035 | CAGR of 34.09% |
| Largest Market | Asia Pacific |
| Base Year | 2025 |
| Forecast Period | 2026 to 2035 |
| Segments Covered | Source, Electrolyzer Type, End Use and Region |
| Regions Covered | North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa |
Market Dynamics
Drivers
Growing government support
Governments play a central role in shaping green hydrogen government policy that provides long-term stability for the market. Around the world, governments continue to set renewable energy targets, establish emission reduction goals, and implement carbon pricing mechanisms, all of which help incentivize demand for green hydrogen. Regulations that support integrating green hydrogen into existing energy systems, such as blending it into natural gas pipelines or supporting fuel cell technology, further reinforce this growth, often backed by direct green hydrogen subsidies.
- In September 2025, Union Minister Pralhad Joshi launched a Rs 100-crore scheme supporting green hydrogen startups, offering funding of up to Rs 5 crore per project. At the accompanying Green Hydrogen R&D Conference, 25 startups showcased their innovations.
- In July 2024, the Ship Financing Portal was launched to improve access to funding for the shipping and broader maritime industry. Created by the European Commission's Directorate-General for Mobility and Transport, the platform offers businesses a set of financial tools to support fleet renewal, retrofitting, efficiency improvements, and reduced environmental impact.
Rising demand for renewable energy solutions
Because renewable energy generation depends heavily on weather conditions, renewable hydrogen storage plays a critical role in balancing supply and demand. Green hydrogen can be produced during periods of surplus renewable generation and stored for later use, either converted back into electricity through fuel cells or used as an industrial feedstock, offering a reliable storage solution that supports grid stability. Many governments, private organizations, and regions have set targets and regulatory policies for transitioning to renewable energy and cutting emissions, often positioning green hydrogen as a key component of their broader green hydrogen energy transition strategies. As demand for renewable energy grows to meet these targets, so too does demand for green hydrogen as a clean energy carrier.
For example, the European Union has set a target to produce approximately 10 million tons of renewable hydrogen, ammonia, and other clean fuel components by 2030, with the European Commission aiming to strengthen hydrogen infrastructure as part of this strategy.
Restraint
Lack of Awareness in Underdeveloped Areas
Underdeveloped regions often lack essential infrastructure, including energy grids and transportation networks, contributing to a persistent green hydrogen awareness gap that makes it difficult to establish and distribute projects effectively. Without this infrastructure, building local production and consumption centers becomes a significant challenge. Many of these regions also face broader economic constraints, including poverty and limited access to capital. Since green hydrogen projects typically require substantial investment and specialized technical expertise, both of which are often scarce in these areas, launching and sustaining such initiatives remains difficult, reinforcing broader green hydrogen infrastructure challenges across these markets.
Limitations with infrastructure
Hydrogen's low energy density makes it inherently challenging to transport and store efficiently, and gaps in hydrogen pipeline infrastructure remain a persistent constraint. Dedicated hydrogen pipelines remain limited, and retrofitting existing natural gas pipelines is often costly and complex. A shortage of bulk transportation infrastructure, including shipping and trucking capacity, further complicates distribution to end users. Green hydrogen also requires specialized facilities as part of broader hydrogen storage technology to prevent leaks and ensure safety, and existing storage infrastructure remains insufficient to support large-scale production and use. Combined with limited refueling station coverage and broader infrastructure gaps, these transportation and storage constraints continue to act as a restraint on market growth.
Opportunity
Rising Investments in Research and Development Activities
Ongoing green hydrogen R&D investment is focused on improving the performance and durability of green hydrogen technologies. Enhancing hydrogen electrolyzer efficiency and lifespan can boost production rates while lowering maintenance costs. Similarly, advances in fuel cell technology continue to improve the efficiency and reliability of hydrogen-powered vehicles and other applications. By addressing one of the market's biggest cost constraints, this research helps drive green hydrogen production costs down, making it more competitive with fossil fuels and encouraging greater investment and adoption across the industry.
Technological Advancements
Continued green hydrogen technology advancements in electrolyzers, renewable energy generation, and decarbonization processes are opening substantial growth opportunities across the market. These advancements are directly supporting the infrastructure needed to scale the industry, including improved hydrogen storage and transportation methods such as high-pressure and cryogenic storage, along with the expansion of hydrogen refueling infrastructure and pipelines. As this infrastructure grows, it creates greater opportunities for widespread green hydrogen adoption.
Challenges
Lack of Awareness in Underdeveloped Areas
As noted, underdeveloped regions continue to face significant infrastructure and financial barriers that make establishing green hydrogen projects difficult. Limited access to capital and technical expertise remains a persistent challenge, continuing to slow broader market growth in these areas.
Segments Insights
Source Insights
Which Source Segment Dominated the Green Hydrogen Market in 2025?
Wind energy hydrogen production led the market in 2025, supported by well-developed large-scale infrastructure and strong capacity factors, particularly across offshore projects. As a reliable source of long-term hydrogen generation, wind energy continues to attract investment from countries looking to scale up hydrogen production, especially in regions where conventional energy resources are limited, or demand is rising quickly.
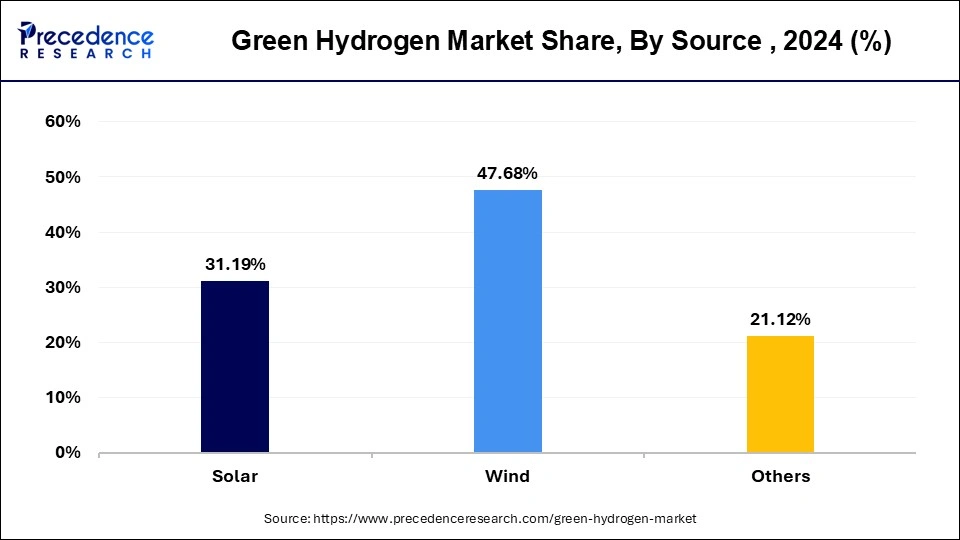
The solar green hydrogen market is expected to be the fastest-growing source segment, driven by rapidly falling photovoltaic module costs and accelerating solar installations worldwide. Rising investment from both companies and governments in solar-powered green hydrogen production is expected to support strong growth throughout the forecast period, further boosted by advanced photovoltaic technologies such as triple-junction cells, perovskite solar cells, photovoltaic-thermal systems, hydrogen photovoltaic units, and concentrating solar power systems.
Global Green Hydrogen Market, By Source, 2023-2025 (USD Million)
| By Source | 2023 | 2024 | 2025 |
| Solar | 1,953.8 | 2,739.1 | 3,842.9 |
| Wind | 2,984.4 | 4,186.9 | 5,878.2 |
| Others | 1,329.3 | 1,854.7 | 2,589.6 |
Electrolyzer Type Insights
Which Electrolyzer Type Dominated the Green Hydrogen Market in 2025?
The PEM electrolyzer market led in 2025, due to its operational flexibility and strong compatibility with variable renewable energy sources. PEM-based hydrogen electrolyzers offer a compact design, fast response times, and high hydrogen purity, making them well suited for both decentralized and large-scale applications. By efficiently converting surplus wind and solar power into hydrogen, PEM electrolyzers continue to support the broader growth of renewable energy systems.
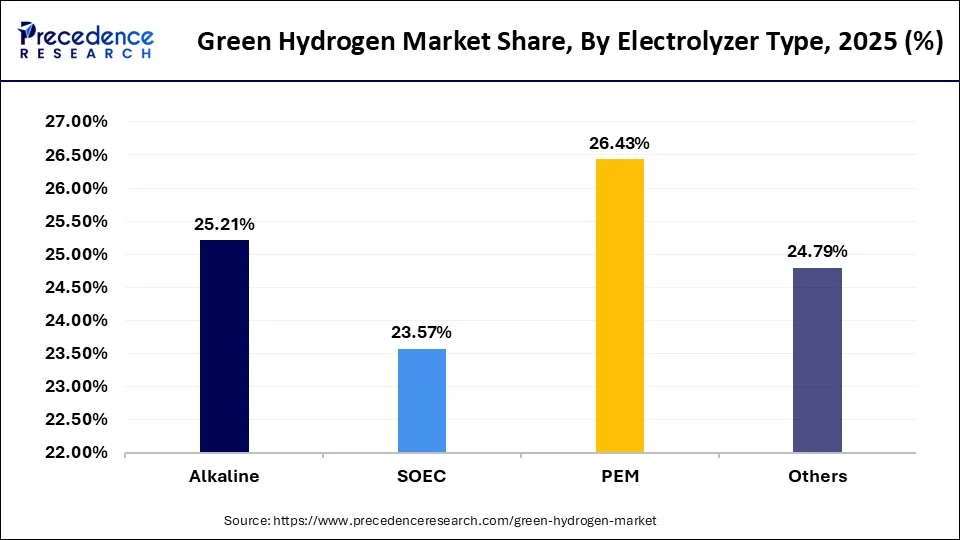
The solid oxide electrolyzer cells market is expected to grow at the fastest rate over the forecast period, owing to its higher efficiency potential and ability to utilize industrial waste heat. SOECs offer notable efficiency advantages over traditional alkaline or PEM electrolyzers, and according to the International Energy Agency (IEA), they can achieve the highest conversion efficiencies among all electrolyzer technologies, making them particularly valuable within industrial hubs.
Global Green Hydrogen Market, By Electrolyzer Type, 2023-2025 (USD Million)
| By Electrolyzer Type | 2023 | 2024 | 2025 |
| Alkaline | 1,578.5 | 2,212.5 | 3,103.5 |
| SOEC | 1,474.5 | 2,067.5 | 2,901.2 |
| PEM | 1,650.5 | 2,316.6 | 3,253.9 |
| Others | 1,564.1 | 2,184.1 | 3,052.1 |
End Use Insights
Which End-Use Segment Dominated the Green Hydrogen Segment in 2025?
The green hydrogen refining market led in 2025, as refineries increasingly shift toward decarbonization and integrate renewable technologies into their operations. The refining industry currently consumes approximately 40 million tonnes of hydrogen annually, primarily for critical processes such as hydrocracking and desulfurizing fuels like diesel and petrol. Rising pressure on refineries to strengthen their sustainability profiles and align with national and international carbon reduction targets continues to support this segment's dominance.
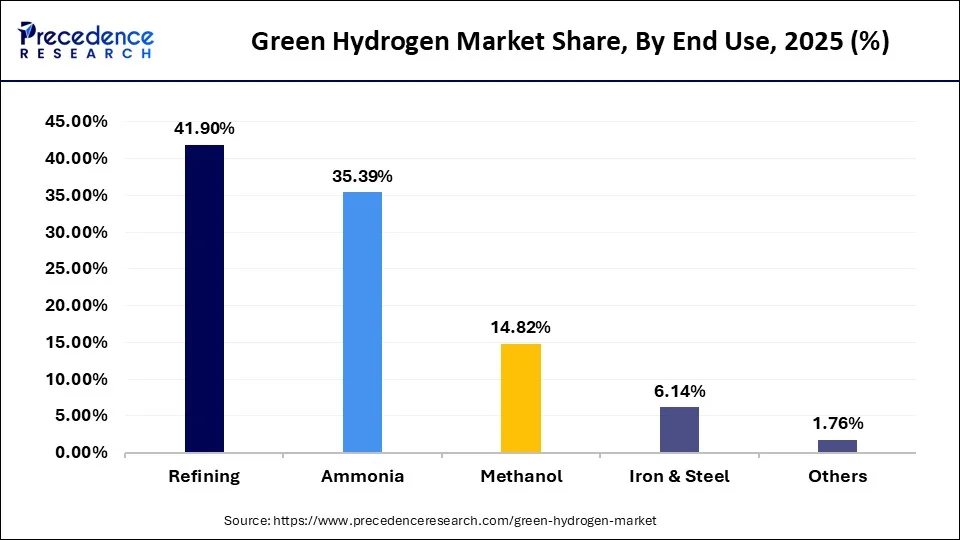
Momentum in green steel production is expected to grow at the fastest rate, driven by the industry's shift toward low-carbon steel. The steel sector remains the top greenhouse gas emitter among heavy industries and the second-largest energy consumer, responsible for approximately 2.6 gigatons of CO2 annually. As emissions from steel production continue to draw scrutiny, demand for green hydrogen is rising in response, with companies such as JSW Steel, Tata Steel, and ArcelorMittal Nippon Steel India already establishing green steel plants.
Global Green Hydrogen Market, By End Use, 2023-2025 (USD Million)
| By End-Use | 2023 | 2024 | 2025 |
| Refining | 2,620.5 | 3,675.1 | 5,157.9 |
| Ammonia | 2,213.2 | 3,104.2 | 4,356.9 |
| Methanol | 924.3 | 1,298.0 | 1,824.0 |
| Iron & Steel | 381.6 | 536.7 | 755.6 |
| Others | 127.9 | 166.8 | 216.4 |
Regional Insights
Which Region Dominated the Green Hydrogen Market in 2025?
Home to more than half the world's population, the Asia Pacific green hydrogen market is expected to play a defining role in shaping the future of global energy and helping the world move toward net-zero emissions. Countries in the region, particularly China and Japan, hold strong strategic advantages across hydrogen storage technology and production, leading globally in electrolyzers, hydrogen storage systems, and hydrogen turbines.
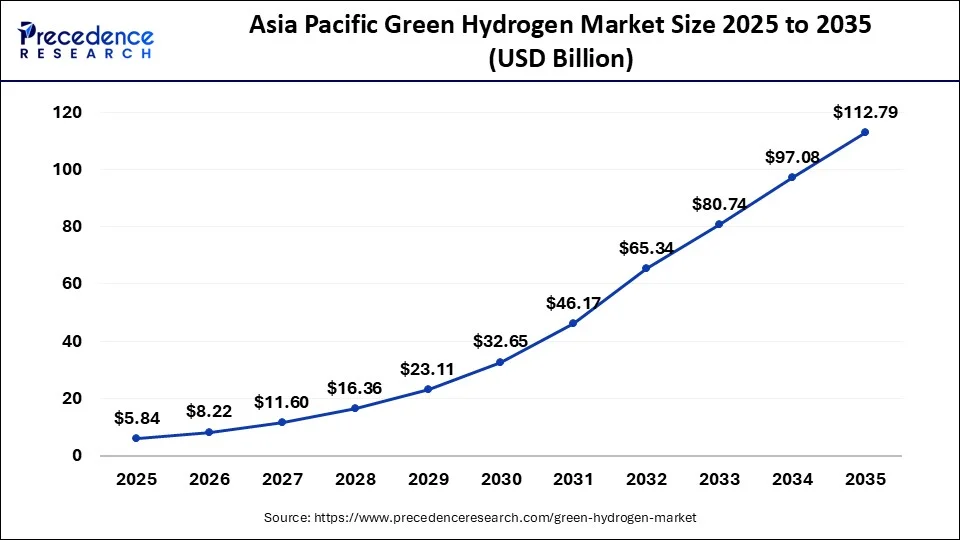
Asia Pacific Green Hydrogen Market Size and Growth 2026 to 2035
The Asia Pacific green hydrogen market size is evaluated at USD 5.84 billion in 2025 and is projected to be worth around USD 112.79 billion by 2035, growing at a CAGR of 34.46% from 2026 to 2035.
India Green Hydrogen Market Trends
The India green hydrogen market continues to show strong momentum. Policy support, including production subsidies, tax incentives, and the development of dedicated green hydrogen corridors, is providing a solid foundation for sector growth and drawing strong interest from both domestic and international players. As a clean fuel produced using renewable sources such as solar and wind, green hydrogen offers India a meaningful opportunity to cut emissions while strengthening energy independence. This aligns closely with the government's National Green Hydrogen Mission, which targets raising green hydrogen's share of India's total hydrogen demand to 46% by 2030, creating substantial opportunities across production and related technologies.
- In May 2025, India's Ministry of New and Renewable Energy launched the Green Hydrogen Certification Scheme (GHCI) to certify green hydrogen production through a transparent, credible framework, aimed at encouraging both domestic production and exports in line with the country's climate and sustainability goals.
China Green Hydrogen Market Trends
The China green hydrogen market leads the Asia-Pacific region, backed by strong government support, major industry players, and abundant solar and wind generation capacity. The Chinese government has set clear emission reduction targets and continues to build out green hydrogen production facilities at scale. Strength in China hydrogen electrolyzer manufacturing allows the country to produce electrolyzers at some of the lowest costs globally, and China is actively exploring green hydrogen applications across transportation, power generation, and potentially the steel industry. With its large population and growing energy needs, China is well positioned to lead global development of green hydrogen technology and infrastructure.
- Europe green hydrogen market size was accounted for USD 2,065.24 million in 2024 and it is growing at a CAGR of 38.30%.
- U.S. green hydrogen market size was reached at USD 1,311.90 million in 2024 and it is growing at a CAGR of 39.34%.
- France green hydrogen market was valued at USD 584.05 million in 2024 and it is growing at a CAGR of 38.44%.
- Germany green hydrogen market size was estimated at USD 629.90 million in 2024 and it is growing at a CAGR of 38.56%.
- China green hydrogen market size was valued at USD 1,352.46 million in 2024 and it is growing at a CAGR of 42.34%.
North America Green Hydrogen Market Trends
The North America green hydrogen market is expected to grow notably in the years ahead, driven by strong government incentives and substantial private sector investment aimed at meeting ambitious green hydrogen decarbonization U.S. goals. AES and Air Products are jointly developing one of the largest green hydrogen facilities planned for the region, integrating extensive renewable energy capacity with electrolyzer production and storage infrastructure. With a shared focus on using renewable energy to produce clean hydrogen for hard-to-decarbonize sectors such as heavy transportation and industry, both the U.S. and Canada continue to position themselves as key hubs for green hydrogen production and use.
U.S. Green Hydrogen Market Trends
The U.S. green hydrogen market continues to expand at a notable pace, driven by growing interest in green hydrogen's potential to address climate challenges, strengthen energy security, and deliver broader economic benefits. In support of this, the U.S. continues to invest heavily in clean hydrogen production incentives, infrastructure development, and targeted research, development, demonstration, and deployment (RDD&D) initiatives.
Europe Green Hydrogen Market Trends
The Europe green hydrogen market is expected to see significant growth over the forecast period, led by several countries pursuing ambitious climate goals alongside major investment in renewable energy infrastructure. The EU hydrogen strategy, under the European Union's Green Deal, aims to build a robust hydrogen economy, with plans to deploy gigawatts of electrolyzer capacity by 2030.
UK Green Hydrogen Market Trends
The UK green hydrogen market continues to be shaped by the government's commitment to achieving net-zero emissions by 2050, driving policies and incentives supporting green hydrogen adoption. Industries central to UK industrial decarbonization, such as steel manufacturing, chemical production, and refining, among the largest contributors to UK carbon emissions, are increasingly turning to green hydrogen as a substitute for fossil fuels, making this shift a key driver of market growth. The UK's green hydrogen sector includes a mix of energy majors, utilities, and specialized technology firms, with companies such as BP, Shell, SSE, ITM Power, and Equinor already announcing large-scale projects focused on industrial decarbonization and renewable energy integration.
Germany Green Hydrogen Market Trends
The Germany green hydrogen market leads in Europe, combining realistic energy targets with strong government investment and advanced technology. The country continues to develop large-scale hydrogen projects powered by wind and solar generation, while also building international partnerships to support hydrogen imports, backed by continued investment in Germany hydrogen infrastructure. Strong government funding continues to support both the development of new hydrogen plants and innovation in clean fuel applications. Germany has also developed significant hydrogen demand within its transportation and steel industries as part of broader emissions reduction efforts, with sustained investment in research, development, and diversified construction partnerships helping the country build strong long-term capabilities.
Latin America Green Hydrogen Market Trends
Favorable government incentives, growing foreign investment, strong decarbonization goals, rising industrial demand for clean energy, and supportive regulatory frameworks continue to shape the Latin America green hydrogen market. The region's abundant wind and solar resources provide a strong foundation for cost-competitive green hydrogen production, while its proximity to major markets in North America and Europe supports growing green hydrogen export Latin America activity.
Market growth across Latin America is further supported by favorable government incentives, decarbonization targets, industrial demand for clean energy, supportive regulation, and rising corporate sustainability commitments. Many governments across the region continue to offer incentives and regulatory support for green hydrogen projects, with several countries actively working to reduce carbon emissions and expand renewable energy through hydrogen development, positioning Latin America as an increasingly important region within the global market.
Chile Green Hydrogen Market Trends
The Chile green hydrogen market is emerging as a key global player in production, due to its exceptional renewable energy potential. Green hydrogen plays a central role in the country's plan to reach Chile carbon neutrality hydrogen goals by 2050, drawing on the solar-rich conditions of its northern region. According to the International Energy Agency (IEA), Chile has the potential to produce up to 160 million tons of green hydrogen annually by 2050, supported by its abundant solar and wind resources.
Brazil Green Hydrogen Market Trends
Brazil is drawing on its diverse renewable energy mix, spanning hydro, solar, wind, and biomass, to strengthen Brazil renewable hydrogen production and position itself as a leading producer of affordable green hydrogen for both domestic use and export. Backed by national programs and an evolving regulatory framework, Brazil continues to attract significant private investment into regional production hubs, particularly around major ports, supporting a strong domestic hydrogen economy while supplying clean energy to international markets such as Germany and the Netherlands.
Middle East and Africa Green Hydrogen Market Trends
The Middle East and Africa green hydrogen market is rapidly emerging as a key global player, supported by substantial, low-cost renewable energy potential from abundant solar and wind resources. National decarbonization strategies, including elements of the broader Saudi Arabia hydrogen strategy under Vision 2030, the UAE's Hydrogen Roadmap, and Oman's Hydrogen Strategy 2040, continue to accelerate investment in production hubs, port infrastructure, and hydrogen-ready industrial clusters.
Saudi Arabia Green Hydrogen Market Trends
Saudi Arabia is positioning green hydrogen as a central pillar of its economic diversification strategy, leveraging abundant solar resources and a strategic geographic location to establish itself as a future energy export powerhouse. The country's green hydrogen sector is marked by substantial government investment in renewable infrastructure, with Saudi Arabia planning $6 billion worth of green hydrogen projects.
One of the most notable projects is the NEOM Green Hydrogen Project in Saudi Arabia, a joint venture between ACWA Power, Air Products, and NEOM. The approximately $8.4 billion project is being developed at Oxagon and is designed to produce up to 600 tonnes of green hydrogen per day, which will be converted into around 1.2 million tonnes of green ammonia annually for export. Construction reached more than 80% completion in 2025, with commissioning and first product availability now expected in 2027.
| Country | Key Regulation/Policy | Definition Standard (CO?e/kg H?) | Primary Incentive Mechanism |
| EU | Renewable Energy Directive (RED III), Delegated Acts, REPowerEU | < 3.38 kg (70% GHG reduction vs. fossil fuel baseline) | Mandates, binding targets for industrial use, ETS/CBAM, subsidies |
| India | National Green Hydrogen Mission (NGHM) | < 2 kg | Production-linked incentives (PLI) for production & manufacturing, transmission fee waivers |
| U.S. | Inflation Reduction Act (IRA) | Varies by tier, lowest tier < 0.45 kg | Production Tax Credits (PTC) up to $3/kg |
| Chile | National Green H? Strategy | Focused on low-carbon certification standards for export | Government financing, strategic partnerships, and conducive export regulations |
Government Investments and Initiatives
- Regional Missions: Various regions continue to strengthen their green energy diversification strategies to meet evolving green hydrogen standards, with governments allocating substantial funding toward supportive programs. India's India SIGHT program and Europe's Important Projects of Common European Interest stand out as leading examples of green hydrogen government initiatives driving this developmental progress, reflecting a broader global commitment to clean hydrogen across industrial and commercial sectors.
- Smart Move: Advanced pilot projects and continued investment in port infrastructure are proving valuable across industries such as chemicals, steel, and shipping. Growing collaboration among these industries is helping build stronger support for a more sustainable hydrogen ecosystem.
- Upgradation: Ongoing clean technology upgrades help the market progress confidently while staying aligned with regulatory requirements, further reinforcing the development of eco-friendly, compliant hydrogen products.
- Clean and Green Energy Promotion: Expanding promotion of clean energy across green building projects and shipping operations continues to generate positive momentum for the market's broader sustainability goals, strengthening the foundation of green hydrogen hubs worldwide.
Strategic Growth Opportunities
High Growth Commercial Opportunities
Green hydrogen commercial opportunities continue to accelerate through clean fertilizer production and broader technology trends supporting eco-friendly production lines, alongside expansion of the green ammonia market. The deployment of intelligent systems marks a significant milestone for green hydrogen production facilities, with sustainability-focused production strategies further strengthening the impact of commercial growth initiatives.
Emerging Technology Opportunities
Advanced technologies continue to benefit manufacturing plants by supporting stronger infrastructure development. Improvements in component and chemical integration are helping meet the efficiency standards required for clean, high-performance products, while modern hydrogen electrolyzers continue to ease the traditional tension between cost and quality.
Geographic Expansion Opportunities
Renewable energy remains central to the mission and vision driving this market forward, positioning it as a key enabler of green energy solutions worldwide. Billions of dollars in regional investment toward new hydrogen plants highlight this growing impact, while expanding green ammonia sales across the Middle East, Africa, and Latin America continue to accelerate broader market growth.
Value Chain Analysis
The green hydrogen value chain spans resource extraction through regulatory compliance, with the broader hydrogen storage systems market forming a critical link in bringing production to end users:
| Stage | Description | Key Players |
| Resource Extraction | Extraction of raw materials essential for green hydrogen production, primarily water, depending on regional availability | N/A |
| Power Generation | Generating electricity through renewable sources such as solar, wind, or hydropower to power the electrolysis process used in green hydrogen production | ACME Group, Avaada |
| Distribution Network Management | Building and maintaining infrastructure to transport and deliver green hydrogen from production facilities to end users and various applications | Indian Oil Corporation Limited (IOCL), Power Grid Corporation of India |
| Energy Storage Systems | Developing and applying safe, effective green hydrogen storage methods, including tank and underground cavern storage, to maintain a steady supply and respond to demand fluctuations | H2e Power |
| Grid Maintenance and Monitoring | Maintaining the renewable energy grid that supports green hydrogen production, ensuring efficient, stable operation while monitoring overall system performance | Central Transmission Utility of India |
| Regulatory Compliance and Energy Trading | Supporting compliance with evolving policy frameworks and environmental regulations | Ministry of New and Renewable Energy |
Competitive Landscape
The green hydrogen market companies operating today reflect a dynamic competitive landscape, shaped by ongoing technological advancement, strong regulatory support, and rising demand for sustainable energy solutions. Leading players such as Air Products, Linde, and Siemens Energy continue to strengthen their market position through strategic partnerships and innovative technology development. Looking ahead, competitive differentiation is expected to shift away from traditional price-based competition toward innovation, technological advancement, and supply chain reliability, positioning companies that prioritize R&D and strategic collaboration for stronger long-term success.
Green Hydrogen Market Companies
- NEL ASA: Develops and supplies electrolysis solutions for green hydrogen production, enabling scalable hydrogen generation from renewable energy sources.
- ITM Power: Designs and manufactures PEM electrolyzers, providing integrated solutions for producing green hydrogen for industrial and mobility applications.
- ENGIE: Invests in renewable energy projects and hydrogen infrastructure, promoting large-scale green hydrogen production and distribution for industrial and power sectors.
- Siemens Energy: Offers electrolyzer technology and hydrogen-ready power solutions, supporting industrial decarbonization and renewable energy integration.
- Air Products Inc.: Produces, distributes, and supplies hydrogen for industrial applications while investing in green hydrogen projects for mobility and energy transition.
- Messer Group GMBH: Develops hydrogen production, storage, and distribution solutions, focusing on green hydrogen supply for industrial and energy applications.
- Plug Power Inc.: Designs fuel cell systems and builds green hydrogen generation and distribution infrastructure to support transportation and industrial sectors.
- Cummins Inc.: Manufactures electrolyzers and hydrogen fuel cell systems, contributing to green hydrogen production and adoption in mobility and industrial applications.
- Air Liquide: Supplies hydrogen production and distribution technologies, including electrolyzers, to accelerate the deployment of green hydrogen in industrial and energy sectors.
- Linde: Provides hydrogen production, liquefaction, and distribution solutions, supporting large-scale green hydrogen projects and industrial decarbonization efforts
Key Companies & Market Share Insights
In the green hydrogen market, there is fierce rivalry to reduce manufacturing costs, develop innovative process technology, expand, and enhance the usage of green hydrogen in end use sectors. The key market players are attempting to grow their market shares by employing various techniques in response to such possibilities in the sector.
Recent Developments
- In June 2026, the Union Minister for New and Renewable Energy and Consumer Affairs, Food and Public Distribution, Shri Pralhad Joshi, inaugurated the Green Hydrogen Certification Portal of India during the National Workshop on “Strengthening the National Green Hydrogen Mission: Through State Policies, Hubs & Infrastructure,” organized by the Ministry of New and Renewable Energy. Developed by the MNRE, the portal aims to facilitate transparent certification and regulatory compliance under the Green Hydrogen Certification Scheme of India.
- In August 2025, Statkraft secured a lease for a piece of land in Shetland next to the abandoned Scatsta Airport to build its 400 MW green hydrogen-to-ammonia plant, Shetland Hydrogen Project 2. The project was going to use excess wind energy from local wind farms that are yet to be built and convert it into ammonia for use as marine fuel and fertiliser. (Source: https://www.hydrogeninsight.com)
- In August 2025, OQ Gas Networks signed a term sheet with Belgium's Fluxys to co-develop hydrogen transportation at agreed sites across Oman. They planned to repurpose natural gas pipelines and build 300 - 400 km of new hydrogen lines by 2030 through OQ Gas Networks, with Fluxys holding a minority operational stake. This was intended to support Oman's green hydrogen development and Net Zero goals. (Source: https://www.pipeline-journal.net)
- In August 2025, India inaugurated its first Make-in-India 1 MW green hydrogen plant at Deendayal Port, Kandla. This facility was established in four months, with a locally manufactured electrolyser, and was also entirely designed and built by locally sourced engineering teams. The facility was built for initial use to power port bus fleets and port street lighting systems, but the state planned and started to develop the project to 10 MW and facilitate the powering of full port operations. (Source: https://www.newsonair.gov.in)
- In August 2025, Copenhagen Infrastructure Partners bought a 70% share in the first 100 MW phase of H2Apex's green hydrogen facility in Lubmin, Germany. CIP had committed €15 million pre-final investment decision, and total EU IPCEI funding amounted to €167 million. Construction was planned to begin in 2026 and commissioning by 2028, and would aim to supply up to 10,000 tonnes per annum. (Source: https://www.h2-view.com)
- In August 2025, Four Zeros Energy partnered with Vergia AS to develop and finance a portfolio of green hydrogen projects throughout the UK. The first of its initiatives, the 20 MW St Austell project in Cornwall, had been selected as a shortlist product under the UK HAR2 allocation round, with production to supply the regional mining operations and carbon reductions by 2028. (Source: https://www.renews.biz)
Segments Covered in the Report
By Source
- Solar
- Wind
- Others
By Electrolyzer
- Alkaline
- SOEC
- PEM
- Others
By End Use
- Refining
- Ammonia
- Methanol
- Iron & Steel
- Others
By Geography
- North America
- U.S.
- Canada
- Europe
- U.K.
- Germany
- France
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of the World
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions


Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample
 sales@precedenceresearch.com
 Schedule a Meeting