
Generative AI Market Size, Key Companies, Company Product Portfolio, Digital Transformation, Technology Investment, Adoption Rates, Customer Acquisition, Company Market Share, and Market Outlook
ICT industry specialist Shivani Zoting estimates the digital remittance market at USD 55.51 billion in 2026, with continued technology adoption expected to take the market to USD 1,206.24 billion by 2035 at a CAGR of 36.97%. Leading digital remittance market providers such as Synthesia, MOSTLY AI Inc., Genie AI Ltd., are expanding their capabilities across segments including by technology/model type, by modality, by deployment mode, by end-user industry and region.
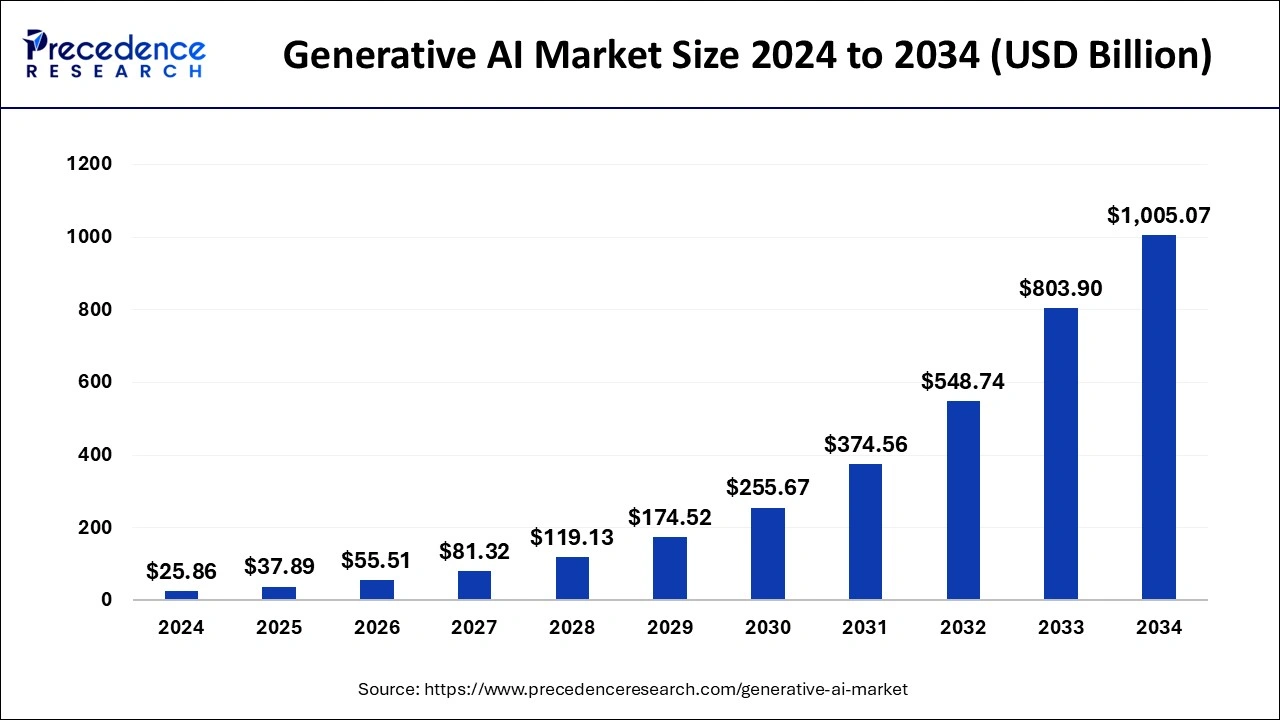
Source: https://www.precedenceresearch.com/generative-ai-market
 Get a Sample
 Table Of Content


What is the Generative AI Market Size?
The global generative AI market size is calculated at USD 37.89 billion in 2025 and is predicted to increase from USD 55.51 billion in 2026 to approximately USD 1,206.24 billion by 2035, expanding at a CAGR of 36.97% from 2025 to 2034. The growing use of technologies such as high-resolution image generation, text-to-image conversion, and text-to-video conversion continues to drive strong demand for generative AI. Additionally, the increasing need to modernize workflows, including automation and remote monitoring across various industries, is expected to further accelerate growth within the generative AI market.
Generative AI Market Key Takeaways
- In terms of revenue, the generative AI market is valued at $37.89 billion in 2025.
- It is projected to reach $1,206.24 billion by 2035.
- The generative AI market is expected to grow at a CAGR of 36.97% from 2026 to 2035.
- The North America market captured 41% revenue share in 2025.
- Asia Pacific market will reach at a CAGR of 27.6% from 2026 to 2035.
- By component, the software segment captured more than 65.50% revenue share in 2025.
- By technology, the transformers segment accounted for the highest revenue share, exceeding 42% in 2025.
- By end-use, the media & entertainment segment captured more than 34% of revenue in 2025.
- By end-use, the business and financial services segment is expected to grow at the fastest rate of 36.4% from 2026 to 2035.
What is Generative AI?
Generative AI refers to a technique that leverages artificial intelligence and machine learning (ML) to develop algorithms capable of generating new digital content, including videos, images, text, audio, or code. These systems work by identifying underlying patterns within input data and using them to produce similar, original outputs. Generative AI offers several key advantages, including the ability to create high-quality content, strengthen identity protection, improve understanding of complex or abstract concepts, and help reduce financial and reputational risks. As a result, generative AI is widely adopted across industries such as healthcare, information technology, robotics, banking, and finance.
Demand for generative AI applications continues to grow across sectors, driven by the expanding use of technologies such as super-resolution imaging, text-to-image conversion, and text-to-video conversion, along with the rising need for organizations to modernize their workflows. Within the healthcare sector specifically, one significant growth driver is the increasing adoption of 3D printing technologies, which are being used to develop a wide range of products from scratch, including organic molecules and prosthetic limbs.
For instance, in 2012, Jen Owen co-founded e-NABLE, also known as Enabling the Future, in the United States. The initiative brings together makers and enthusiasts from around the world to build a global volunteer network dedicated to designing and rapidly 3D printing prosthetic devices. Alongside this, market growth is being further supported by the rising popularity of generative AI, which is helping power chatbots capable of creating more natural, effective conversations that improve overall customer satisfaction. A generative chatbot, in particular, is an open-domain program that constructs original language responses in real time, rather than relying on a fixed set of pre-defined replies.
Technological Advancement
Key technological advancements shaping the generative AI market include computer vision, deep learning, multimodal AI, and natural language processing (NLP). Computer vision enables AI systems to interpret and generate videos and images with greater accuracy, while advancements in NLP, particularly through large language models (LLMs), are enhancing the ability to generate and understand human-like text. Deep learning continues to evolve as well, with ongoing innovation across techniques such as reinforcement learning, generative adversarial networks (GANs), and variational autoencoders (VAEs).
Multimodal AI is further expanding these capabilities by enabling content generation across multiple formats, including video, text, and images, drawn from diverse media sources. As demand for these technologies continues to grow across industries, ongoing innovation within the generative AI market is helping accelerate business growth, both for established companies and new entrants, while driving broader market expansion.
Generative AI Market Statistics
- According to McKinsey's 2025 State of AI survey of nearly 2,000 organizations across 105 countries, 79% of companies now use generative AI in at least one business function, up sharply from 33% in 2023.
- Gartner projects that worldwide AI spending will total $2.59 trillion in 2026, marking a 47% increase over the previous year, underscoring the scale of enterprise investment flowing into AI and generative AI technologies. (Source: https://www.200oksolutions.com)
- Stanford's HAI AI Index Report found that the estimated value of generative AI tools to U.S. consumers reached $172 billion annually by early 2026, with the median value per user tripling between 2025 and 2026.
According to BCG's 2026 report on AI investment trends, companies plan to allocate 1.7% of total revenue to AI initiatives in 2026, more than double the 0.8% recorded in 2025, reflecting growing executive confidence in long-term returns. - EY's AI-Driven Productivity and Investment Survey found that the share of companies allocating at least a quarter of their IT budget to AI is expected to nearly double, from 27% to 52%, highlighting the rapid reprioritization of enterprise technology spending toward AI.
Market Outlook
- Industry Growth Overview: The generative AI market in the United States continues to grow substantially, driven by rising usage and increasing demand for AI-generated content across industries.
- Global Expansion: America remains at the forefront of AI adoption, continuing to shape enterprise AI trends that ripple outward to other regions around the world.
- Major Investors: Prominent investors such as Andreessen Horowitz, Sequoia Capital, Microsoft, Google, Nvidia, and SoftBank Vision Fund continue to provide strong financial backing to U.S.-based generative AI companies, reinforcing the country's leadership position in this space.
Market Scope
| Report Coverage | Details |
| Market Size in 2025 | USD 37.89 Billion |
| Market Size in 2026 | USD 55.51 Billion |
| Market Size by 2035 | USD 1,206.24 Billion |
| Growth Rate from 2026 to 2035 | CAGR of 36.97% |
| Base Year | 2025 |
| Forecast Period | 2026 to 2035 |
| Segments Covered | Component, Technology, End-Use |
| Regions Covered | North America, Europe, Asia-Pacific, Latin America, Middle East & Africa |
Market Dynamics
Drivers
Audio synthesis represents another major application area, with generative AI capable of transforming computer-generated voices into remarkably natural, human-like speech. Platforms such as Synthesia have become widely recognized for their text-to-speech and text-to-video capabilities, allowing users to create polished AI voiceovers and video content in just a few clicks. These tools are increasingly used in advertising and media production, enabling businesses to quickly turn a simple script into a professional explainer video, product tutorial, or presentation, complete with natural-sounding narration.
Application in healthcare
Generative AI is also making a significant impact in healthcare. When combined with technologies such as 3D printing and CRISPR, it can help design prosthetic limbs, organic molecules, and other products from the ground up, while also supporting earlier cancer detection and more effective, personalized treatment planning. For instance, in April 2020, IBM Research developed CogMol, a generative AI framework that used deep learning to design novel drug candidate molecules targeting SARS-CoV-2, helping accelerate early-stage COVID-19 drug discovery efforts.
Beyond healthcare, growing demand for advanced manufacturing involving complex designs, along with the need to reduce component size while improving automotive performance, is expected to further drive growth in the global generative AI market. This trend is encouraging automotive manufacturers to increase R&D investment and adopt generative design techniques, helping fuel continued market expansion.
Identity protection as well as image processing
In October 2022, generative AI avatars were deployed in news reports regarding the prejudice towards LGBTQ people in Russia to obfuscate the identities of interviewees. The LGBTQ community has been under threat in Russia for quite a while, and generative AI helped some community members protect their identity and ensure their safety.
Restraints
Lack of skilled personnel
While generative AI allows machines to create new content effectively, it also has some limitations. Generative AI is still in its early stages, necessitating a trained workforce and significant investment in implementation. According to IBM's global AI adoption index report 2022, approximately 34% of respondents thought that a shortfall of AI knowledge, skills, or expertise prevented industries from adopting AI. As a result, the need for an experienced workforce and high implementation expenses are anticipated to hinder the market's growth.
Opportunities
Investment in R&D and technological advancement
Major market players such as Apple and Microsoft, based in the US, are increasing their investments in R&D. Additionally, these businesses are investigating technologies such as AI and machine learning (ML). Worldwide Technology, an AI service provider, launched an initiative focused on AI and ML in May 2020, with some of the most advanced experiments and work on generative AI planned.
The generative AI market is expected to see strong growth opportunities as more businesses continue developing and experimenting with embedding generative AI capabilities into their products and services. Market growth is further being driven by the rising use of generative AI in building immersive virtual worlds within the metaverse, along with the growing trend of creating digital artwork using only text-based descriptions, both of which continue to expand the technology's real-world applications.
- In November 2024, Language-learning platform Duolingo announced it to introduce its generative AI-powered video-calling feature, 'Call with Lily,' in India as part of its strategy to drive monetization. The feature allows users to engage in interactive, conversation-based practice with Lily, a virtual character, offering an immersive language-learning experience.
Challenges
Control limitations
Despite this momentum, generative AI can occasionally exhibit instability or unpredictable behavior in certain scenarios. For example, a Generative Adversarial Network (GAN) may produce outputs that fail to meet expectations without offering a clear explanation, making it difficult to identify the root cause or determine the best solution.
Several challenges continue to pose restraints on the market's growth. One key limitation is pseudo image generation. Since generative AI relies on analyzing large volumes of existing data, it cannot create entirely original images but instead produce novel combinations of previously learned information. Security remains another significant concern, as generative AI's ability to create highly realistic fake images and photos raises the risk of identity theft, fraud, and counterfeiting. Additionally, data privacy concerns are increasingly relevant, particularly in healthcare applications, where generative AI often relies on collecting and processing sensitive personal information.
Segments Insights
Component Insights
The generative AI industry is broadly divided into software and services. The software segment held the largest market share at 65.50 percent in 2024 and is expected to maintain its dominance throughout the forecast period. This growth is influenced by several factors, including rising incidents of fraud, overestimated AI capabilities, unpredictable outcomes, and growing data privacy concerns, all of which continue to shape how software solutions are developed and deployed. Generative AI itself refers to a technology built on algorithms capable of producing new content, including audio, code, images, text, 3D models, and video, with tools like ChatGPT serving as a widely recognized, user-friendly example.
Generative AI relies on foundation models, deep learning systems capable of performing multiple complex tasks simultaneously, to generate entirely new content rather than simply categorizing or recognizing existing data. As these models continue to grow more powerful through advanced machine learning techniques, generative AI software is expected to play an increasingly important role across industries such as fashion, entertainment, and infrastructure. For instance, in December 2022, the Laboratory for Artificial Intelligence in Design (AiDLab) in Hong Kong hosted a fashion show featuring designer collections developed with the help of its generative AI tool, AiDA, an AI-based Interactive Design Assistant capable of generating original fashion designs based on a designer's creative input.
The services segment, meanwhile, is expected to register the fastest CAGR over the forecast period. Growth in this segment is being driven by increasing concerns around stock market trading forecasts, data security, fraud detection, and risk factor modeling. Cloud-based generative AI services are also gaining popularity due to their flexibility, scalability, and cost-effectiveness, further accelerating growth within the services market. For example, Amazon Web Services (AWS) launched Amazon Bedrock and a suite of generative AI services in April 2023, following an earlier announcement in June 2022 introducing new cloud platform capabilities that enable developers to more efficiently write code, train datasets, and integrate AI directly into their applications.
Technology Insights
Generative AI technology can be broadly categorized into variational autoencoders, generative adversarial networks (GANs), diffusion networks, and transformers. In 2025, transformers generated the highest revenue share, exceeding 42 percent, driven largely by the growing popularity of transformer-based applications such as text-to-image generation. Transformer models are specifically designed to learn contextual relationships between words within a phrase or larger body of text. They achieve this through a technique known as self-attention, which allows the model to evaluate the relative importance of different words in a sequence based on context. This approach differs from traditional recurrent neural network (RNN) models, which process input sequentially and lack a broader, global understanding of the full sequence.
DALL-E, for example, is a transformer model capable of interpreting text and converting it into corresponding images. Another notable transformer model, GPT-3, developed by OpenAI, a San Francisco-based AI research organization, can generate emails, poetry, and other written content that closely resembles human writing.
The diffusion network segment is expected to register the fastest CAGR over the forecast period. Image generation has become increasingly essential across industries, supporting high-value services for private businesses, public sector organizations, and government institutions alike, as demand for advanced image creation capabilities continues to grow. Artificial intelligence, particularly recent advancements in natural language processing (NLP) and generative AI, continues to capture global attention due to its ability to meaningfully boost productivity across a wide range of job functions. Tools such as OtterPilot, which automatically generates meeting notes for executives, GitHub Copilot, which helps developers quickly build complete code, and Mixo, which enables business owners to rapidly launch websites, all illustrate this growing real-world impact.
The reinforcement learning-augmented models segment is expected to grow at a CAGR of 24.10% during the forecast period. This segment plays a critical role within the broader generative AI pipeline, shifting the focus from simply generating new content to producing outputs that align more closely with human preferences, real-world needs, and specific goals. This is largely achieved through reinforcement learning from human feedback (RLHF), a technique that has become fundamental to fine-tuning large-scale generative AI models with greater precision and relevance.
End-Use Insights
The end-user segment of the generative AI market spans media and entertainment, healthcare, business and financial services, IT and telecom, and automotive and transportation, alongside smaller but growing segments such as security, aerospace, and defense. Media and entertainment led the market, generating more than 34 percent of total revenue in 2023, exceeding USD 1.5 billion, driven largely by the use of generative AI to enhance advertising campaigns and content creation.
Generative AI's impact extends well beyond media, touching industries such as banking and healthcare through its ability to create new data or content using advanced machine learning algorithms. This technology is fueling a wave of creative innovation, enabling new forms of literature, music, and art, while opening up fresh avenues for self-expression. Within healthcare, generative AI is being used to support the development of novel medications and therapies, analyze medical imagery, and assist in diagnostic decision-making. In the financial sector, it is helping drive the development of new financial products and services, supporting deeper financial data analysis, and improving market forecasting accuracy. Additionally, generative AI continues to play a growing role in analyzing audience behavior and enabling more personalized, data-driven content creation across industries.
During the forecast period, the business and financial services segment is expected to grow at the fastest rate of 36.4%. The market expansion in this sector is attributed to the growing use of artificial intelligence (AI) and machine learning (ML) in the industry to stop fraud, secure data, and satisfy the changing demands of various stakeholders in financial services.
Modality Insights
The text segment held the largest share of the global generative AI market at 37.90 percent in 2025, reflecting its foundational role in the technology's ongoing expansion and development. Since the early breakthroughs in natural language processing, this segment has continued to strengthen its presence and now serves as a core component of multimodal systems capable of generating video, images, and audio. Continued advancements in generative AI have further accelerated growth across applications such as translation, summarization, code generation, and conversational agents like chatbots.
The multimodal segment is expected to register a CAGR of 23.40% over the forecast period. This growth has been driven by rising demand for content conversion, particularly within the media and entertainment, IT, and telecom industries. Capabilities such as text-to-image, video-to-text, image-to-text, and multimodal search continue to position this segment at the forefront of generative AI innovation. With its advanced, cross-format approach, the multimodal segment holds significant potential to reshape the broader generative AI landscape and drive a meaningful shift in future market growth.
Deployment Mode Insights
The cloud-based segment held the largest share of the global generative AI market at 71.80% in 2024. This segment encompasses various cloud deployment models, including public, hybrid, and private cloud, with most large organizations adopting cloud-based systems to strengthen operational reliability and drive performance growth. As a key enabler of generative AI's continued expansion, cloud-based deployment provides the essential computational power, accessibility, and scalability required to support large-scale AI models. This growth continues to be reinforced by strong, ongoing collaboration between AI developers and cloud service providers.
The edge-based and device-local segment is expected to register a CAGR of 21.50% over the forecast period. This segment focuses on running AI models directly on local hardware rather than relying entirely on centralized cloud servers. This shift is gaining momentum due to key advantages such as reduced latency, improved data privacy, and lower bandwidth costs, positioning edge-based deployment as an increasingly attractive alternative within the broader generative AI ecosystem.
End-user Insights
The IT and telecom segment held the largest share of the global generative AI market at 20.60 percent in 2025. This industry has been at the forefront of integrating generative AI tools and capabilities into everyday workflows, making it a pivotal driver of the technology's broader deployment and development. By providing essential connectivity, data processing capabilities, and infrastructure support, IT firms continue to lead generative AI adoption, while telecom companies are experiencing improved scalability as a result. Together, these advancements are unlocking new revenue opportunities and enabling more personalized service offerings across the industry.
The healthcare and life sciences segment is expected to register a CAGR of 21.70% over the forecast period. The healthcare and life sciences industry is entering a transformative phase driven by growing generative AI adoption, particularly in areas such as drug discovery and personalized medicine. Generative AI is also helping improve administrative efficiency, support the design of new proteins and molecules, and automate complex research analysis. In addition, the technology is enabling virtual assistants for patient support and remote monitoring. Key advancements in this space continue to focus on greater precision, reduced costs, and significantly faster research and development timelines.
Regional Insights
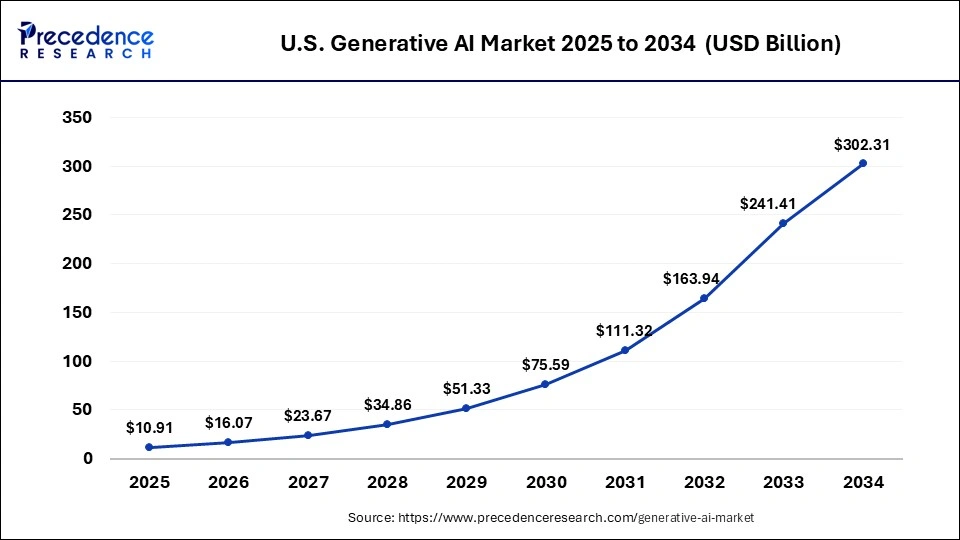
U.S. Generative AI Market Size and Growth 2026 to 2035
The U.S. generative AI market size was estimated at USD 10.91 billion in 2025 and is predicted to be worth around USD 363.21 billion by 2035, at a CAGR of 37.53% from 2026 to 2035.
North America: U.S. Generative AI Market Trends
This is enabled by the confluence of colossal amounts of personal capital and the availability of the highest-quality innovation systems in the world. The current proliferation of AI into technology, finance, healthcare, and defense is motivated by the leading technology companies, research centers, and access to a skilled workforce. The governmental contact offers the moral AI implementation, and the eminent demand of the AI specialists only increases the rivalry and makes the expenses higher.
North America led the global generative AI market, generating more than 41 percent of total revenue in 2025. This trend is expected to continue throughout the forecast period, supported by the growing adoption of pseudo-image generation technologies and rising concerns around banking fraud. Companies such as Meta, Google LLC, and Microsoft are expected to continue playing a key role in driving generative AI development across the region.
North America's continued dominance in the generative AI market is further reinforced by strong contributions to innovation, risk management strategies, and AI governance frameworks, allowing the region to advance with both confidence and strong economic support. Within the U.S., the Department of Homeland Security plays a notable role in overseeing the safe and secure deployment of artificial intelligence technologies nationwide.
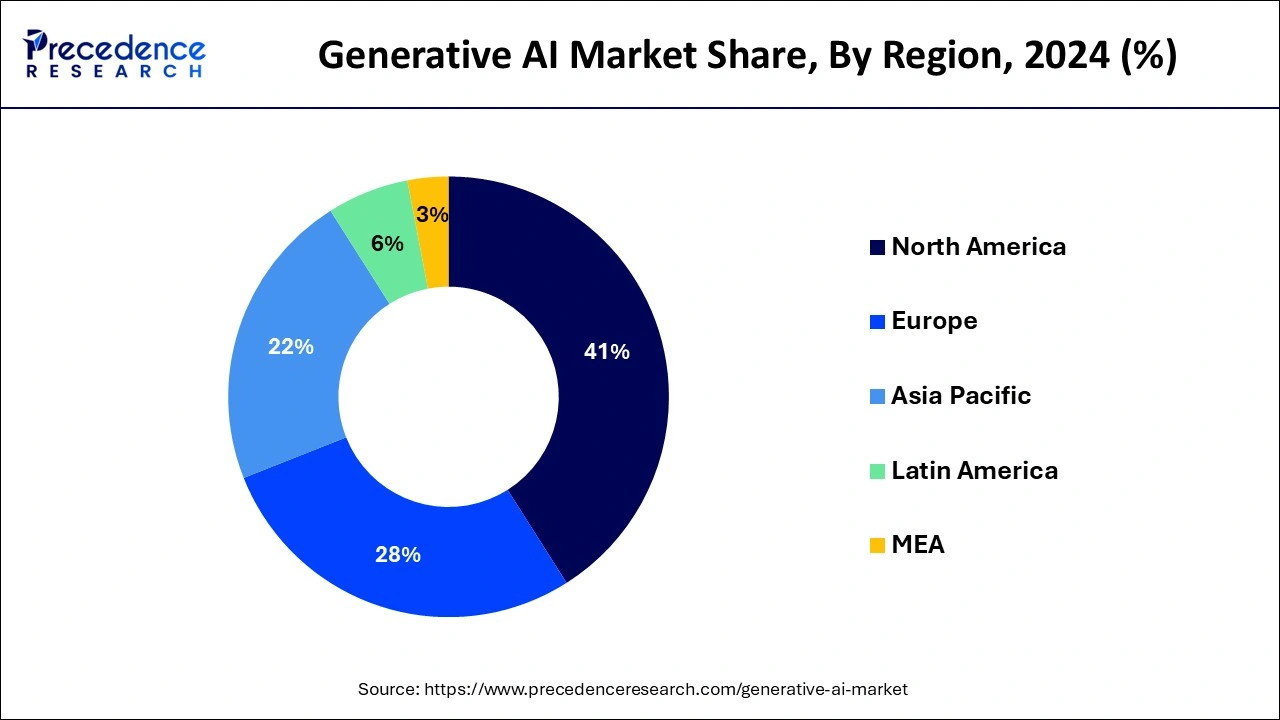
During the forecast period, Asia Pacific will grow at the fastest CAGR. The region's growth in generative AI is fueled by expanding government initiatives and a rise in the deployment of AI-based applications.
Asia Pacific is expected to register the fastest CAGR over the forecast period, driven by expanding government initiatives and the growing deployment of AI-based applications across the region. This growth is further supported by ongoing technological innovation and increasing adoption of generative AI in emerging economies such as China, Japan, and South Korea. Companies across these markets continue to invest heavily in AI, helping optimize growth across sectors such as commerce, manufacturing, and media. Additionally, strong government support for AI research and development throughout the region continues to accelerate overall market expansion.
- In October 2024, IndiaAI and Meta announced the establishment of the Center for Generative AI, Srijan at IIT Jodhpur, along with the launch of the “YuvAi Initiative for Skilling and Capacity Building” in partnership with the All-India Council for Technical Education (AICTE), for the advancement of open-source artificial intelligence (AI) in India.
What Are the Driving Factors of the Generative AI Market in Europe?
Europe is expected to grow at a significant rate over the forecast period, with ethical AI regulations and compliance with the EU AI Act playing a key role in supporting this growth momentum. Countries such as Germany, France, and the UK continue to invest heavily in generative AI applications across industrial, healthcare, and finance sectors. Backed by strong research institutions and supportive regulatory frameworks, businesses across the region are well positioned for growth, reflecting rising confidence and increasing adoption of generative AI across virtually every part of the European economy.
Germany Generative AI Market Trends
Germany continues to benefit from its strong presence in industrial AI applications, supported by decades of experience in manufacturing, automotive engineering, and Industry 4.0 adoption. The country's well-established regulatory frameworks encourage companies to develop and deploy AI responsibly and ethically, backed by clear government support. By combining technological innovation with strong business confidence, Germany continues to encourage new startups and established enterprises alike to adopt generative AI solutions across a wide range of industries.
Asia Pacific: India Generative AI Market Trends
India has been winning over as the most important outlet in Asia-Pacific, with quick digital acceptance and integration of enterprises. The technology-friendly government is rendering AI ubiquitous in e-commerce, manufacturing, media, and services, and most of the Indian population is purchasing the AI-powered products. The Indian market is becoming the global leader in AI consumer usage as generative AI is providing it with the aspects of automation, personalization, and productivity.
India Generative AI Market Trends
India has emerged as one of the most important markets in the Asia-Pacific region, driven by rapid digital adoption and growing enterprise integration of AI technologies. Supportive government policies are helping accelerate AI adoption across sectors such as e-commerce, manufacturing, media, and services, while a large share of the Indian population continues to embrace AI-powered products. As generative AI continues to enable greater automation, personalization, and productivity, India is increasingly positioning itself as a global leader in consumer AI adoption.
Top Companies in the Generative AI Market & Their Offerings
- Synthesia: Synthesia delivers an artificial video platform with the closest to human avatars, support for many languages, and professional content creation for industries in the U.S.
- MOSTLY AI Inc.: MOSTLY AI creates very similar synthetic data for U.S. companies, allowing the training of algorithms that are safe and simultaneously private and compliant.
- Genie AI Ltd.: Genie AI uses huge language models to supply AI-based legal support, including contract creation, checking, and analyzing for American clients.
Generative AI Market Companies
- Synthesia
- MOSTLY AI Inc.
- Genie AI Ltd.
- Amazon Web Services, Inc.
- IBM
- Google LLC
- Microsoft
- Adobe
- Rephrase.ai
- D-ID
Recent Developments
- In May 2025, LinkedIn launched a generative AI tool that lets users uncover tailored job listings just by describing their ideal role in their own words. The technological initiative in applications is allowing individuals to explore and develop their expertise.
- In May 2025, IBM Think 2025 highlighted Watson X.data's role in generative AI. The data platform will address roadblocks in scaling generative and agent-based AI, contributing to the growth of the generative AI market.
- In May 2025, Kama.ai launched trustworthy AI hybrid agents. The merging of deterministic and generative AI delivers trusted, brand-safe virtual agents. It is guided by human values, with a new enterprise retrieval augmented generation (RAG) process.
- In February 2025, Google Cloud and Accenture launched the Generative AI Center of Excellence in Saudi Arabia, providing businesses with industry expertise, technical knowledge, and product resources to build and scale applications using Google Cloud's generative AI portfolio and accelerate time-to-value.
- In April 2025, the Cannes Film Market launched Village Innovation, a new venue dedicated to technology and innovation (including Gen AI) in the film industry. The venue will bring together the bulk of activities from Cannes Next, the market's flagship program dedicated to innovation in the film industry, as well as activities stemming from the all-new ImmersiveMarket, which revolves around XR and immersive professionals.
- In May 2025, TalentSprint, a global leader in DeepTech education, announced an executive-friendly, four-month Generative AI Foundations and Applications program. Created for both emerging and current working professionals, the program provides cutting-edge AI skills and hands-on experience in the rapidly evolving world of Generative AI.
- SXiQ, an Australia-based digital transformation services company with expertise in cloud applications, platforms, and cybersecurity, was acquired by IBM in November 2021.
- ALTAIR ENGINEERING INC announced the release of Thea Render V3.0 in March 2021. The Thea Render is a 3D renderer that uses state-of-the-art and unbiased graphic refining unit engines.
- Altair announced in February 2021 that it had adopted GE Aviation's Flow Simulator.
- In May 2020, Archistar, an Australian property intelligence platform that combines architectural design with artificial intelligence to inform property decision-making, closed a USD 6 million Series A funding round led by AirTree to accelerate international growth and expand its product and engineering team.
Segments Covered in the Report
By Technology/Model Type
- Transformer-based Models
- Large Language Models (LLMs)
- Vision Transformers
- Diffusion Models
- Generative Adversarial Networks (GANs)
- Variational Autoencoders (VAEs)
- Autoregressive Models
- Flow-based Models
- Hybrid Architectures
- Reinforcement Learning-augmented Generative Models
By Modality
- Text
- Natural Language Generation
- Code Generation
- Summarization
- Translation
- Conversational Agents (Chatbots)
- Image
- Image Synthesis
- Image Inpainting
- Style Transfer
- Super Resolution
- Audio
- Music Generation
- Voice Cloning
- Text-to-Speech (TTS)
- Video
- Video Generation
- Video Prediction
- Animation Generation
- 3D & AR/VR
- 3D Model Generation
- Virtual Environment Design
- Multimodal
- Text-to-Image
- Image-to-Text
- Video-to-Text
- Multimodal Search
By Deployment Mode
- Cloud-based
- Public Cloud
- Private Cloud
- Hybrid Cloud
- On-Premises
- Edge-based / Device-local
By End-user Industry
- IT & Telecom
- Media & Entertainment
BFSI (Banking, Financial Services, Insurance) - Healthcare & Life Sciences
- Retail & E-commerce
- Manufacturing
- Automotive
- Education
- Government & Defense
- Legal Services
- Marketing & Advertising Agencies
- Gaming
- Others
By Geography
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East & Africa (MEA)
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions


Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample
 sales@precedenceresearch.com
 Schedule a Meeting