
Regenerative Medicine Market Size, Key Companies, Company Market Share, Patient Volume, Treatment Adoption Rates, Pricing Analysis, Regulatory Landscape, Competitive Positioning, and Demand Forecast
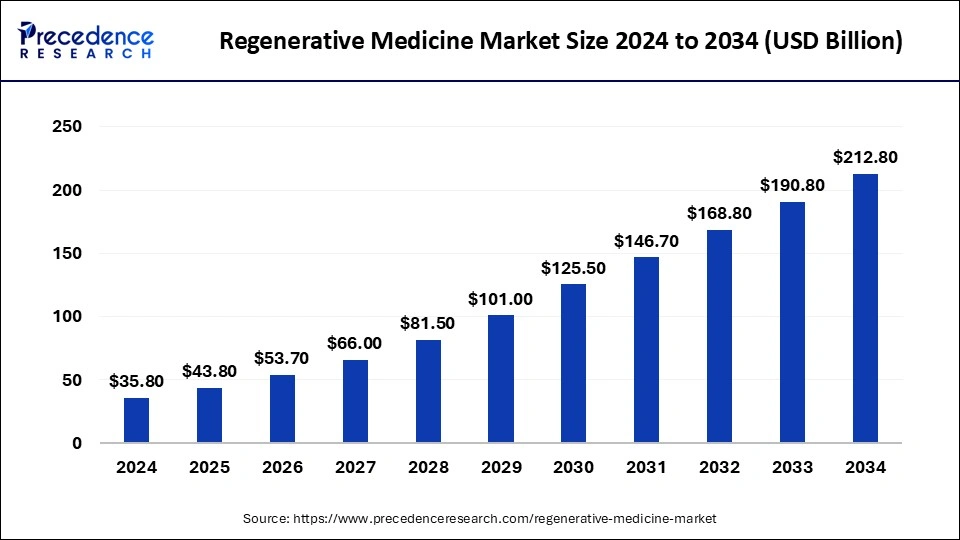
The regenerative medicine market size Valued at USD 53.65 billion in 2026, the global regenerative medicine market is projected to reach USD 234.85 billion by 2035, expanding at a CAGR of 18.29% from 2026 to 2035. Market growth is driven by rising investments in stem cell research, advancements in gene therapy and tissue engineering, increasing prevalence of chronic diseases, supportive regulatory initiatives, and growing adoption of personalized regenerative therapies across healthcare.
Source: https://www.precedenceresearch.com/regenerative-medicine-market
 Get a Sample
 Table Of Content


What is the Regenerative Medicine Market Size?
The global regenerative medicine market size is predicted to increase from USD 53.65 billion in 2026 to approximately USD 234.85 billion by 2035, expanding at a CAGR of 18.29% from 2026 to 2035. Due to rising investments in stem cell research, increasing demand for advanced therapies, technological innovations, and the growing prevalence of chronic diseases and age- related disorders.
Key Takeaways
- The global regenerative medicine market is projected to grow from USD 53.65 billion in 2026 to USD 234.85 billion by 2035, registering a CAGR of 18.29% from 2026 to 2035.
- North America accounted for approximately 43% of the market revenue in 2026, supported by advanced clinical infrastructure, established treatment centers, and strong biotechnology capabilities.
- A 2025 regulatory assessment identified 322 active cell and gene therapy clinical trials, highlighting the growing development pipeline for advanced regenerative treatments.
- Genetically modified cell therapies represented approximately 53% of the 322 identified clinical programs, while gene therapies accounted for another 25%.
- The broader cell therapy landscape includes more than 10,000 clinical trials, with oncology accounting for approximately 56% of these trials.
- More than 100 clinical trials of human pluripotent stem cell-derived products had received regulatory approval by the end of 2026, with over 1,200 patients dosed.
- Asia Pacific is emerging as an important regenerative medicine development and manufacturing region, driven by expanding biotechnology investment, lower manufacturing costs, and growing clinical infrastructure.
Overview - Regenerative Medicine is Moving from Experimental Platforms Toward Commercially Scalable Therapies
The market covers cell therapy, gene therapy, tissue engineering, biomaterials, and selected regenerative products. Commercial activity is moving away from conventional stem-cell concepts and toward approved cell and gene therapies, engineered tissues, gene editing, iPSC-derived products, and scalable allogeneic platforms. Science alone no longer drives the opportunity. Clinical validation, reimbursement, manufacturing costs, treatment-center capacity, and the ability to deliver reproducible outcomes matter just as much.
The full analysis sets market boundaries across therapeutic and tissue-regeneration products. It measures revenue by modality, cell source, technology, indication, application, end user, treatment setting, pricing model, and commercial maturity.
Key Coverage
- North America representing approximately 43% of 2025 revenue
- Cell and gene therapies as the principal high-value growth engines
- Oncology, orthopedics, wound care, rare diseases, ophthalmology, and neurological applications
- Autologous versus allogeneic treatment economics
- Manufacturing, reimbursement, regulatory, and clinical adoption analysis
Segmentation Analysis - Cell Therapy Provides the Commercial Base While Gene Editing and Advanced Gene Therapy Expand the Highest-Value Pools
We segment the market into cell therapy, gene therapy, tissue engineering, and other regenerative products. We also break it down by cell source, therapeutic approach, application, end user, and geography.
Cell therapy remains a central commercial category. It includes hematopoietic stem cells, mesenchymal stem cells, immune-cell therapies, CAR-T, TCR-based therapies, TILs, fibroblast therapies, and emerging iPSC-derived cells. Gene therapy is becoming more strategically important because it targets the underlying genetic cause of disease instead of simply replacing damaged tissue. Tissue engineering forms its own pool, covering engineered tissues, vascular grafts, regenerative matrices, scaffolds, and related biomaterial products.
Based on our application analysis, oncology, orthopedics, wound care, rare diseases, cardiovascular disorders, ophthalmology, neurology, and immunological conditions as key revenue pools. Oncology stands out because cell therapies can command very high treatment values. Orthopedic and wound-care applications offer broader, procedure-based opportunities.
Key Coverage
- Cell therapy by cell source and therapeutic platform
- Gene therapy and gene-editing approaches
- Tissue engineering and biomaterials
- Oncology and rare-disease applications
- Orthopedic and wound-regeneration applications
- Hospital, specialty-clinic, and treatment-center demand
- Largest, fastest-growing, and emerging segments
What is Driving Regenerative Medicine from Pipeline Expansion Toward Commercial Validation?
The pipeline keeps growing. A 2025 regulatory assessment counted 322 active cell and gene therapy clinical trials. Genetically modified cell therapies made up about 53% of these programs, and gene therapies made up another 25%. Advanced therapeutic platforms clearly sit at the center of industry development. The wider cell-therapy landscape is far larger, with more than 10,000 clinical trials, and oncology accounts for about 56% of them. Cancer remains the biggest clinical application pool.
Pipeline size is becoming a weaker predictor of market growth. What matters more is whether a therapy can move from proof of concept to real commercial use. That means showing durable clinical outcomes, winning regulatory approval, scaling manufacturing, securing reimbursement, and fitting into treatment-center workflows. Rising chronic and degenerative disease rates, advances in gene editing, better biomaterials and growing clinical evidence all strengthen demand. But complex manufacturing, high treatment costs, long-term safety requirements, payer uncertainty, and limited treatment infrastructure still hold commercialization back.
The winners will be the platforms that solve the whole commercialization equation, not just the efficacy question. Technologies that scale manufacturing, simplify treatment, widen patient eligibility, and deliver durable outcomes have the best chance of turning big pipelines into steady revenue. That opens the door for standardized allogeneic approaches, automated manufacturing, and technologies that cut reliance on individualized treatment workflows.
The full report examines pipeline distribution, treatment eligibility, clinical attrition, and manufacturing scalability, along with reimbursement constraints and treatment center capacity. We also benchmark development activity by modality, application, clinical stage, and geography. The goal is simple: show where pipeline activity will turn into sales and where structural barriers could slow it down.
How are High Treatment Costs and Evolving Reimbursement Models Reshaping Regenerative Medicine Economics?
Prices in regenerative medicine cover a wide range. Tissue-regeneration products usually follow conventional procedure-based reimbursement, while advanced cell and gene therapies can cost millions as a one-time payment. Several recently approved therapies list at more than USD 2 million per treatment.
Price alone says little about commercial value unless you also consider how long the treatment lasts and what it means for lifetime healthcare costs. For one-time therapies, payers now weigh the upfront cost against the repeat procedures, chronic treatment, disease progression, and long-term care the therapy might prevent. As a result, attention is shifting to cost per treatment, manufacturing cost per dose, administration expenses, lifetime treatment value, and patient eligibility.
In our view, reimbursement will decide how much of the clinical pipeline becomes addressable for market revenue. Therapies with durable outcomes and clear cost offsets can better support premium pricing. High manufacturing costs, complex administration, and uncertain long-term results can limit adoption, even when the therapy works well clinically.
The full report benchmarks treatment pricing, manufacturing economics, reimbursement coverage, and outcomes-based contracts. It also compares how pricing differs by therapy type, indication, treatment setting, and region, so you can see which conditions best support broader adoption.
Which Technologies are Most Likely to Expand the Addressable Regenerative Medicine Market?
The technology frontier is evolving beyond traditional cell transplantation to include gene edited cells, iPSC, in vivo cell programming, next generation viral vectors, nonviral delivery, engineered tissues, organoids, biomaterials and automated manufacturing. Over 100 clinical trials of human pluripotent stem-cell derived products have received regulatory approval by the end of 2024, and more than 1,200 patients have been dosed. These clinical advances are driving the value of pluripotent stem-cell technology closer to commercialization, but challenges around scalability and manufacturing costs remain.
The next wave of competition will focus less on science and more on consistency, safety, manufacturing, and access to patients. Gene editing; CAR-T, TCR, TIL and NK platforms; and AAV and lentiviral vectors are expanding the range of cellular engineering approaches. Meanwhile, tissue scaffolds, biomaterials, organoids, and engineered tissues are pushing regenerative medicine beyond systemic cell and gene therapies into structural tissue repair and functional replacement.
In-vivo cell programming could change industry economics in a big way. These approaches move part of the cellular engineering into the patient's body instead of relying fully on ex vivo manufacturing. That could cut individualized processing and simplify treatment. Automation, closed manufacturing systems, nonviral delivery, and standardized iPSC-derived products could speed the shift by making production more reproducible and less labor-intensive.
The full report covers iPSC-derived therapies, gene editing, cell-therapy platforms, viral vectors, in vivo programming, and tissue scaffolds, plus patents and R&D intensity. Each technology is benchmarked on clinical maturity, manufacturing requirements, scalability, and commercial readiness. That shows which platforms can best grow the patient and revenue pool.
How is Competition Evolving Across Regenerative Medicine's Distinct Value Pools?
The competitive landscape stays fragmented because it mixes high-value pharmaceutical therapies, biotechnology platforms, tissue engineering, orthopedic regeneration, advanced wound care, and manufacturing technologies. Each follows a very different commercial model. Company size alone doesn't show competitive strength. Revenue concentrated in pharmaceutical therapies can hide the strategic weight of specialists in tissue regeneration, biomaterials, manufacturing, or emerging cell and gene therapy platforms.
Companies now fall into several groups: those with approved commercial therapies, those with late-stage pipelines, those with differentiated technology platforms, those with established tissue-regeneration workflows, and those whose manufacturing capabilities support the wider ecosystem. Competitive advantage now depends on a combination of clinical validation, platform scalability, manufacturing control, regulatory execution, and geographic reach, not on pipeline size alone. Companies with commercial products already have treatment pathways and reimbursement experience. Pipeline-focused specialists may hold technologies with greater growth potential, but they carry higher development and commercialization risk.
The most important competitive divide appears at the modality level. Cell and gene therapy leaders compete on clinical outcomes, pipeline depth, manufacturing scalability, and treatment economics. Tissue-engineering and regenerative-product specialists compete on clinical workflow integration, product differentiation, surgeon or provider adoption, and manufacturing consistency. That makes modality-level benchmarking essential for seeing where concentration is high, where specialist positions hold up, and where new technologies could disrupt established value pools.
The full report benchmarks global leaders and biotechnology specialists on commercial versus pipeline exposure, approved-product concentration, and manufacturing capabilities. We combine that company-level view with modality-level benchmarking to assess strength across products, pipelines, technology, and regional presence.
Which Companies are Capturing Commercial Revenue as Regenerative Medicine Moves from Pipeline Development to Scaled Adoption?
Commercial concentration varies a lot by modality. Companies with approved therapies, established treatment pathways, manufacturing scale, and proven reimbursement models capture more of the revenue. Tissue engineering, wound care, orthopedic regeneration, and enabling technologies stay fragmented. Even among recent launches, the gap is clear: Casgevy generated about, while Elevidys generated about USD 899 million. Commercial maturity, indication breadth, treatment-center readiness, and manufacturing capacity can produce big differences in revenue, even within the same broad category.
Market share is becoming more modality-specific instead of concentrating evenly across the market. Approved cell and gene therapies can build concentrated revenue pools around a few proven franchises. Fragmented product categories continue to support many specialists, regional providers, and technology suppliers. This represents a significant discontinuity between current and potential leaders as companies with comparatively smaller revenues can have substantial value through end-of-pipeline products, differentiated platforms, manufacturing expertise or expansion into new indications.
Revenue share alone doesn't capture competitive strength in regenerative medicine. A fair assessment also looks at modality exposure, pipeline maturity, approval status, share gains or losses, manufacturing capabilities, and the balance between established products and future growth assets. The full report provides modality-specific market shares, estimated company shares, Top 5 and Top 10 concentration, and commercial-versus-pipeline positioning.
Which Product and Application Positions are Creating the Strongest Competitive Differentiation in Regenerative Medicine?
Portfolio benchmarking shows that positioning differs sharply between companies with broad regenerative-medicine platforms and specialists built around one technology or application. We assess companies across cell therapy, gene therapy, tissue engineering, wound care, orthopedic regeneration, ophthalmology, vascular regeneration, and enabling technologies. Three factors increasingly shape differentiation: the number of commercially proven products, the depth of the investigational pipeline, and the ability to extend a platform across several indications.
A broad portfolio gives diversification, but specializing in a specific application can build a stronger position in a targeted clinical niche. Oncology, rare genetic diseases, cartilage repair, chronic wounds, vascular repair, and ophthalmology are established arenas, where clinical validation and treatment workflows create real barriers to entry. Neurological regeneration, cardiovascular repair, iPSC-derived tissues, and autoimmune applications are emerging areas. Little commercialization has happened there so far, which leaves more room for portfolio expansion and differentiated positioning.
Judge a portfolio by breadth and depth, not by product count alone. The full report benchmarks approved versus investigational assets, application leadership, portfolio gaps, and commercial white spaces. It shows where companies hold established franchises, where competition is heating up, and where unmet clinical needs may support future opportunities.
Which Technologies are Most Likely to Reshape Regenerative-Medicine Economics by Reducing Manufacturing Complexity?
Our technology benchmarking covers gene editing, iPSC platforms, CAR-T, TCR, TIL, NK cells, AAV vectors, nonviral delivery, in vivo cell programming, engineered tissues, biomaterials, and automated manufacturing. Competition is shifting from therapeutic differentiation alone toward the economics of production and delivery. Companies disclosed about USD 12 billion in cell and gene therapy investment during 2025, and much of the M&A activity targeted next-generation platforms.
Technologies that cut personalized manufacturing needs could give companies a real edge. In vivo cell-therapy approaches matter especially here, because they can reduce or skip parts of individualized ex vivo processing. That processing often requires complex workflows, specialized facilities, and long preparation times. Automation, nonviral delivery, scalable cell platforms, and engineered manufacturing processes should grow in importance as developers try to raise throughput while keeping treatment costs and operational complexity under control.
In our view, technology leadership should be measured by how well a company turns scientific differentiation into scalable, repeatable, commercially viable manufacturing. The full report benchmarks platforms by clinical maturity, manufacturing complexity, scalability, and commercial applicability. It also tracks investment and M&A relevance. The result is a clear list of technologies that could change cost structures, widen treatment access, and create new competitive positions.
How are Regional Capabilities and Manufacturing Footprints Reshaping Competitive Positioning in Regenerative Medicine?
North America emerges as the largest regional market. It has established infrastructure, advanced clinical capabilities, and a dense concentration of treatment centers. Asia Pacific is gaining ground as clinical infrastructure expands; manufacturing costs stay lower, biotechnology investment grows, and domestic development programs multiply. Regional competitiveness now depends less on market size and more on whether a region can combine GMP capacity, specialized manufacturing, clinical infrastructure, and local commercial access.
Manufacturing localization is becoming a key competitive lever for therapies that need complex cell processing or viral-vector production. Companies accessing scalable GMP facilities, cell-processing infrastructure, vector manufacturing, treatment centers, and regional R&D reduce logistics complexity and respond faster to local demand. This makes China, Japan, South Korea, and India more relevant to the industry's long-term manufacturing and development footprint. Europe and North America remain important centers for commercialization, research, and advanced clinical infrastructure.
Regional advantage will depend on how well a company integrates manufacturing, clinical, R&D, and commercial capabilities. Presence alone won't do it. The full report benchmarks regional revenue, manufacturing footprint, GMP capacity, localization strategies, and CDMO relationships across the U.S., Europe, China, Japan, South Korea, India, and other relevant markets. You can compare both current regional strength and future expansion potential.
Which Strategic Investments and M&A Themes are Most Directly Addressing Scalability and Patient Access?
Strategic activity in 2025 was focused on in-vivo CAR-T, gene editing, allogeneic platforms, regenerative tissue, and manufacturing capability. In-vivo cell therapy is beginning to differentiate itself in M&A. There is a clear emphasis on reducing the manufacturing and logistical burden of autologous therapies. Investors are targeting platforms that offer significant improvements in scalability, streamlining of treatment, and expansion of patient access.
These deal structures can provide more than just technology licensing. In-vivo approaches can reduce the need for individual ex-vivo processing. Allogeneic approaches can allow for more standardized production and distribution. The investments in manufacturing and facility expansion suggest that the companies are trying to control production capacity, quality, and supply. Access to technology and manufacturing at scale has become critical to M&A logic in the regenerative medicine space.
Expect future deals to tie scientific differentiation more closely to commercialization and manufacturing economics. The full report tracks acquisitions, platform licensing, technology partnerships, manufacturing investments, and new facilities from 2024 through 2026. For each deal, it examines the rationale, the technology targeted, the manufacturing implications, and the geographic goals.
Which Capabilities Will Determine Long-Term Leadership Across the Regenerative-Medicine Competitive Landscape?
We assess top active organizations. For each, we study headquarters, ownership, revenue, regenerative-medicine exposure, commercial products, pipeline depth, manufacturing footprint, R&D capabilities, partnerships, and key vulnerabilities. Positions differ widely by business model. Some companies rely on commercial scale and approved products, while others earn their strategic relevance through specialized platforms, late-stage pipelines, manufacturing capabilities, or differentiated applications.
Long-term leadership will go to companies that can turn clinical validation into scalable commercial execution. We segregate companies as commercial scale leaders, cell-therapy specialists, gene-therapy specialists, tissue-engineering leaders, manufacturing-platform providers, application specialists, regional leaders, and emerging challengers. This grouping gives more strategic insight than comparing revenue or pipeline size alone, because regenerative medicine brings together very different commercial models, manufacturing needs, and clinical pathways.
In our view, competitive positions make sense only as combinations of capabilities, never as a single performance metric. The full report provides detailed profiles covering products, clinical programs, manufacturing, intellectual property, partnerships, M&A, and strategic priorities, along with each company's strengths and vulnerabilities. We keep the assessment qualitative and evidence-based and don't apply a proprietary scoring index.
Where are the Most Attractive White Spaces Emerging Between Unmet Clinical Need and Scalable Manufacturing?
The opportunity landscape stays broad. It spans allogeneic therapies, iPSC-derived products, in vivo cell programming, gene editing, engineered vascular tissues, cartilage regeneration, neurological applications, ophthalmology, chronic wound care, lower-cost manufacturing, and emerging-market localization. Clinical need alone doesn't define the best opportunities. They appear where a real unmet need meets a path to repeatable manufacturing, practical treatment delivery, and sustainable reimbursement.
Easing the manufacturing burden of individualized therapies is one of the clearest white spaces across the field. Autologous approaches often need patient-specific processing and specialized treatment workflows, which limit scalability and hurt economics. Platforms that deliver comparable outcomes through more standardized production can reduce operational complexity, open up more treatment sites, and expand the addressable patient population. That makes allogeneic approaches, in vivo programming, automated manufacturing, and localized production especially relevant to future commercial models.
Five factors should be weighed together when judging a white space: clinical unmet need, technology readiness, manufacturing feasibility, geographic access, and reimbursement potential. The full report maps technology and geographic white spaces, underserved indications, and lower-cost treatment models. It shows where emerging platforms can overcome today's clinical, operational, or economic limits.
How Do Entry Barriers, Supply Constraints and Pipeline Intensity Shape Competitive Rivalry in Regenerative Medicine?
The industry pairs high scientific and regulatory entry barriers with intense development activity. A defined global regulatory pipeline includes more than 300 active cell and gene therapy programs, and broader cell-therapy development reaches thousands of clinical programs. At the same time, access to specialized vectors, GMP capacity, cell-processing inputs, and qualified manufacturing infrastructure remains tight. Established capabilities give strong protection, but constant innovation keeps competitive pressure high.
Both suppliers and buyers have a considerable impact on the market. The supplier power is medium-high due to the differentiation of manufacturing inputs and the necessity to build up a validated GMP infrastructure. The buyer power is also relatively high since hospital networks and payers have a strong impact on adopting a particular medical technology through reimbursement and treatment-site policies and economics. The threat of entry is low-medium due to scientific and clinical-barrier complexities, manufacturing validation and regulatory requirements, and capital-intensive infrastructure development. The threat of substitutes is medium since there is a variety of treatment approaches for most indications, including pharmaceutical, surgical, transplant, biological, and supportive care.
Competitive advantage comes from controlling scarce capabilities while showing enough clinical and economic value to win adoption. The full report applies Porter's Five Forces to supplier constraints, buyer influence, entry barriers, substitutes, and competitive intensity. It also looks at how pipeline density, regulatory complexity, and changing treatment economics could reshape industry structure.
Regenerative Medicine Market Segments
By Product Type
- Cell Therapy
- Gene Therapy
- Tissue Engineering
- Other Regenerative Products
By Cell Source
- Autologous Cells
- Allogeneic Cells
- Stem Cells
- Somatic Cells
- Induced Pluripotent Stem Cells (iPSCs)
By Technology
- Gene Editing
- CAR-T Cell Therapy
- T-Cell Receptor (TCR) Therapy
- Tumor-Infiltrating Lymphocyte (TIL) Therapy
- Natural Killer (NK) Cell Therapy
- Viral Vector Technology
- Nonviral Delivery Systems
- In Vivo Cell Programming
- Biomaterials and Tissue Scaffolds
- Organoids and Engineered Tissues
- Automated Manufacturing Technologies
By Application
- Oncology
- Orthopedics and Musculoskeletal Disorders
- Wound Care and Wound Healing
- Rare Genetic Diseases
- Cardiovascular Disorders
- Ophthalmology
- Neurological Disorders
- Immunological Disorders
- Vascular Regeneration
- Other Applications
By End User
- Hospitals
- Specialty Clinics
- Regenerative Medicine Centers
- Academic and Research Institutes
- Other Healthcare Providers
By Treatment Setting
- Inpatient Settings
- Outpatient Settings
- Specialized Treatment Centers
By Pricing and Reimbursement Model
- One-Time Treatment Payments
- Procedure-Based Reimbursement
- Outcomes-Based Contracts
- Long-Term Payment Models
- Conventional Healthcare Reimbursement
By Commercial Maturity
- Approved Commercial Therapies
- Late-Stage Clinical Candidates
- Early-Stage Clinical Candidates
- Preclinical and Emerging Technologies
By Region
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia Pacific
- Latin America
- Brazil
- Rest of Latin America
- Middle East and Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
For inquiries regarding discounts, bulk purchases, or customization requests, please contact us at sales@precedenceresearch.com
Frequently Asked Questions


Ask For Sample
No cookie-cutter, only authentic analysis – take the 1st step to become a Precedence Research client
 Get a Sample
.webp)
 sales@precedenceresearch.com
 Schedule a Meeting